
Study on Industrial Accelerator Act: EU industry may not be able to meet battery demand at all
The EU is currently debating the draft “Industrial Accelerator Act” (IAA), which aims to boost production and competitiveness within the Union. ACEA has now released a study examining whether Europe’s battery supply chain is capable of meeting the requirements of this legislative package. The outcome: a significant gap.
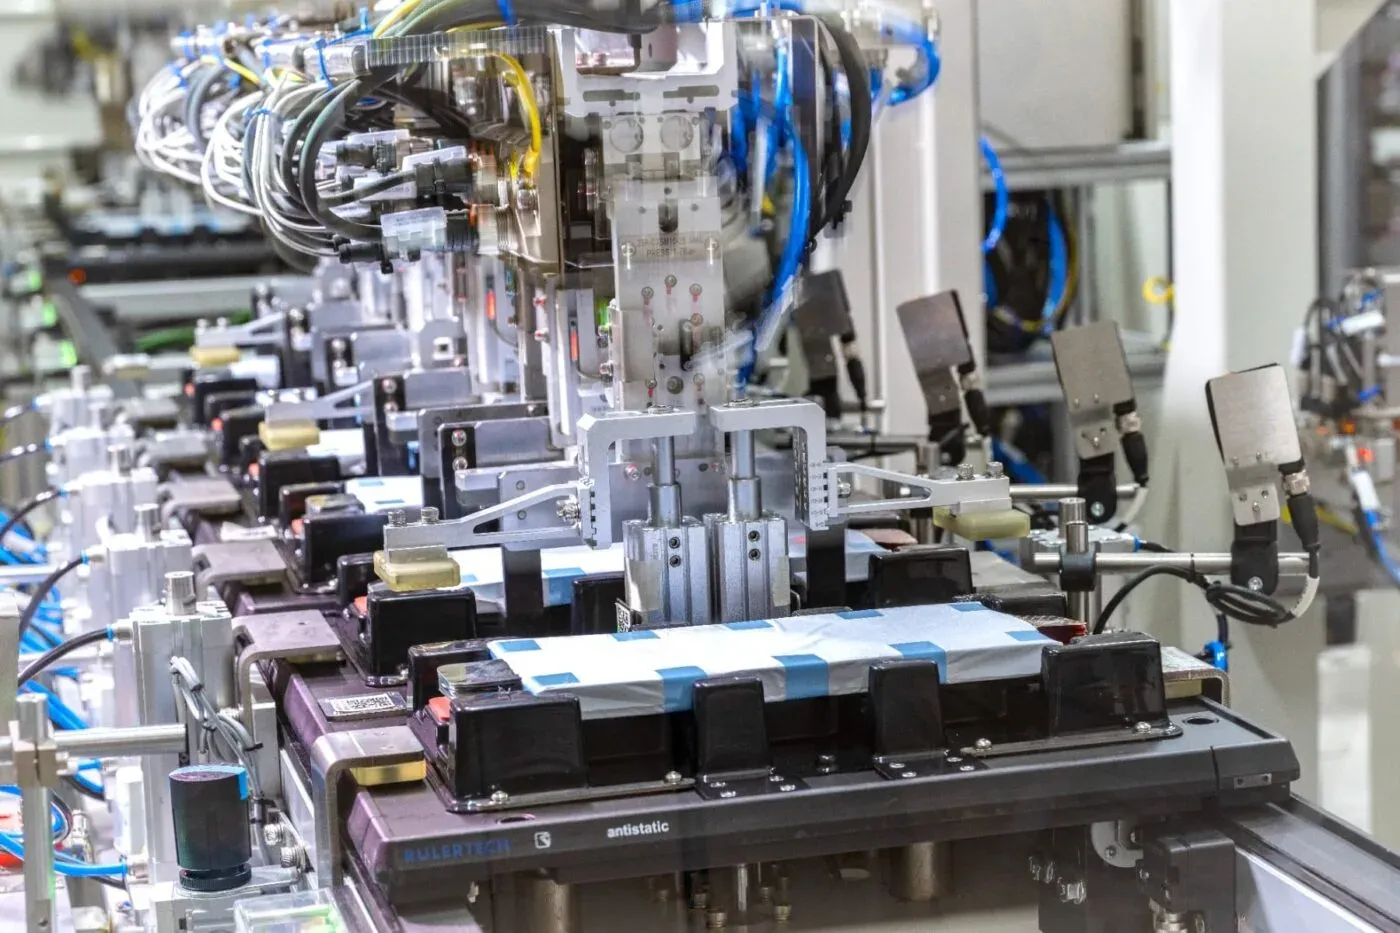
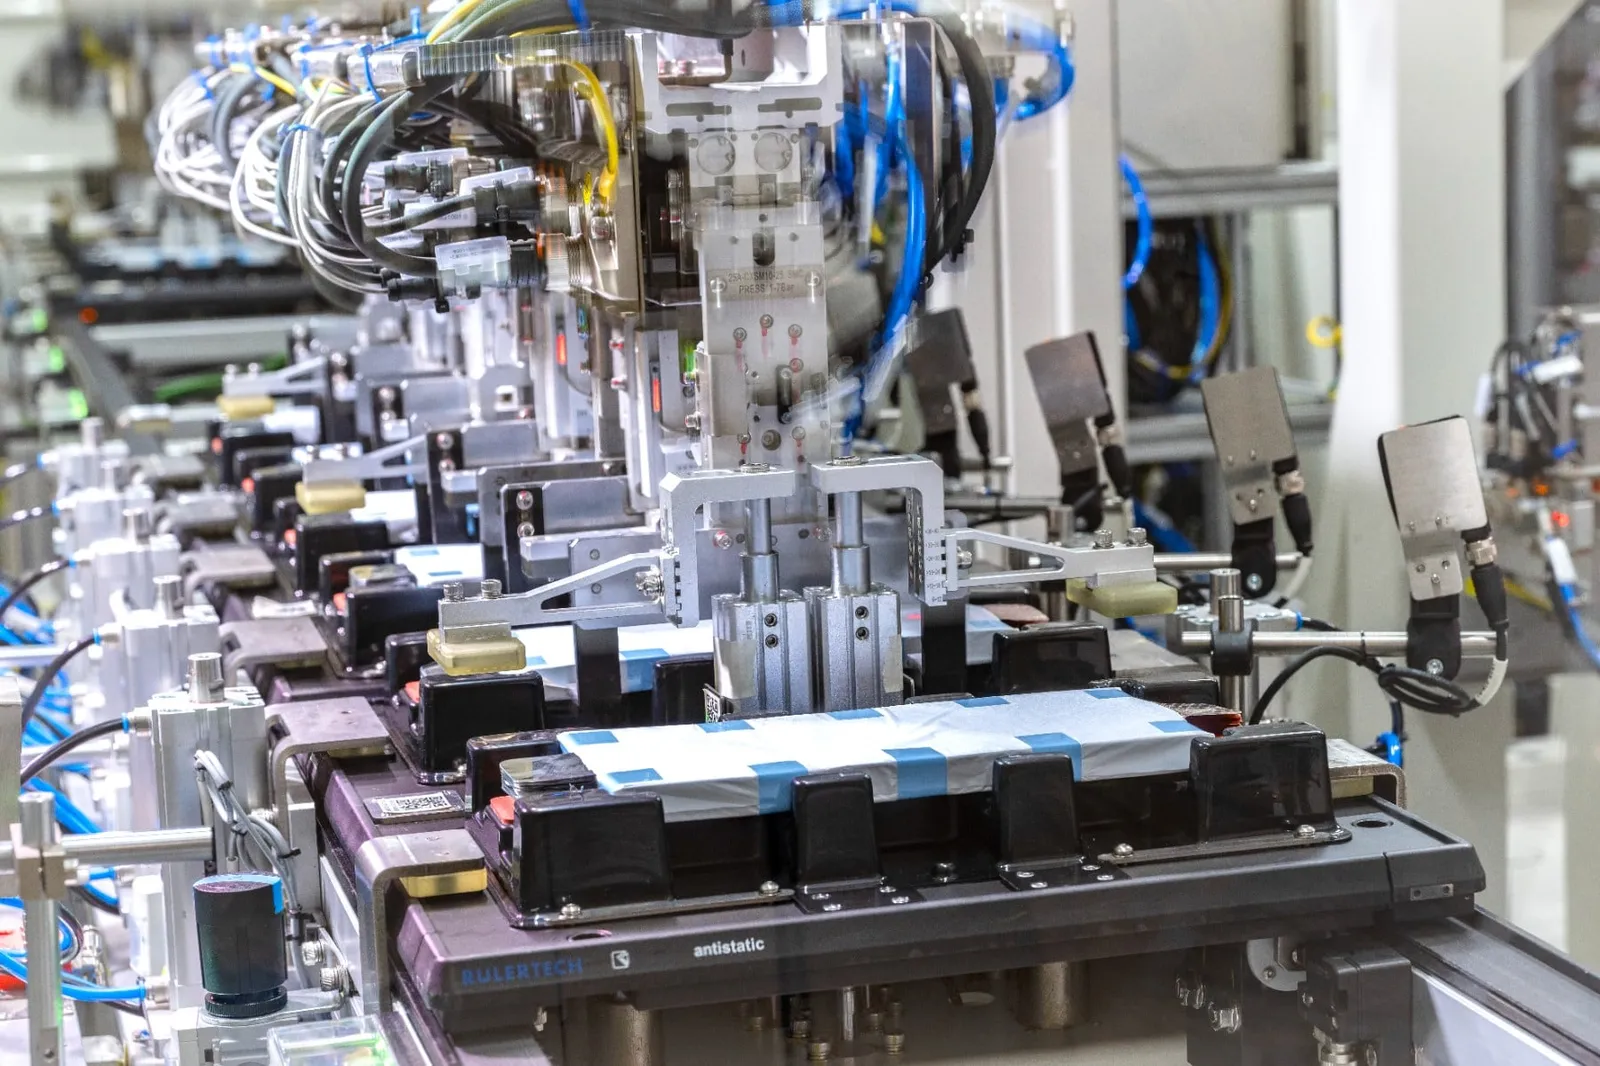
Battery production at VW’s subsidiary PowerCo in Salzgitter.
Image: PowerCo
The European Automobile Manufacturers’ Association (ACEA) commissioned analysts at Mobility Global to conduct this study, which now presents a 19-page executive summary titled “IAA Impact Assessment: European Battery Supply Chain Outlook.” The document examines the potential consequences for companies in the battery industry and the entire automotive sector if the IAA is implemented as proposed by the Commission in March. Important note: The law has not yet been finalized, as negotiations in the European Parliament and the Council are still ongoing.
Up front: the main message of the study is that strict requirements for localizing battery production are not sufficient to ensure the establishment of a domestic battery value chain in practice. The analysts indeed identify “profound, structural barriers to localizing battery production,” and overcoming these is likely to take years.
But step by step: According to the proposed IAA draft, requirements for batteries used here are set to be introduced in two phases. Six months after the law takes effect (“around 2027–2028,” according to the study authors”), batteries must contain three components originating from the EU, including battery cells. Three years after adoption (“around 2030–2031”), this number is supposed to rise to five EU-origin components, including battery cells, the battery management system, and active cathode materials (CAM).
Mobility Global has now examined three scenarios regarding varying levels of industry demand for European batteries. The result shows that in all scenarios, supply cannot keep up with demand — despite the expected growth in European battery cell production to 306 GWh by 2032. This means that in the medium term, there will not be enough IAA-compliant batteries to fully supply the electric vehicle industry in the European Union. The study covers the next ten years.
ACEA concludes: “Limited supply will remain the main obstacle to expanding the range of vehicles eligible for ‘Made in the EU’ incentives. For example, around 3 million vehicles might not qualify for these incentives due to insufficient supply if the IAA comes into effect in 2028.” The so-called “Made in the EU” incentives are another aspect of the legislative package aimed at ensuring that national programs primarily subsidize the EU’s own economy.
ACEA further emphasizes that the challenge for medium- and heavy-duty commercial vehicles is even more pronounced than for passenger cars: “The gap between supply and demand will continue to widen here by 2032, reaching 23 GWh, with demand being roughly four times the available European supply,” according to a key finding of the study.
The association identifies weak battery value chains in the EU as a major issue. The specific points cited by the analysts are:
- Most planned European gigafactories focus on NMC batteries, while demand is increasingly shifting toward cheaper LFP batteries
- Batteries manufactured in Europe remain significantly more expensive than imported ones.
ACEA concludes that the findings “highlight the need for a realistic and economically viable approach to localization.” The effectiveness of IAA will ultimately depend not only on the ambition of its requirements “but also on whether Europe can create the necessary preconditions, competitive operating conditions, and investment frameworks to implement them in practice.”
The report also includes recommendations from the association on how to bridge the gap between aspirations and reality. ACEA advises:
- Massive investments in the upstream sector: To produce CAM and AAM locally and meet demand, substantial investment must be directed toward developing the essential upstream components—such as facilities for manufacturing precursor materials (pCAM) and for graphite refinement (AAM).
- Shift in policy toward operational support: Policy makers must move beyond merely financing factory construction to subsidizing ongoing operating costs—especially high energy expenses—and simultaneously issuing environmental permits expeditedly to accelerate project timelines.
rules to formally include strategic trade partners is essential; this would enable Europe to bypass high domestic energy costs and utilize international joint ventures to bridge the material gap.
acea.auto, acea.auto (Study, PDF)