
SNE Research: Chinese OEMs increasingly dominate the global electric vehicle battery market
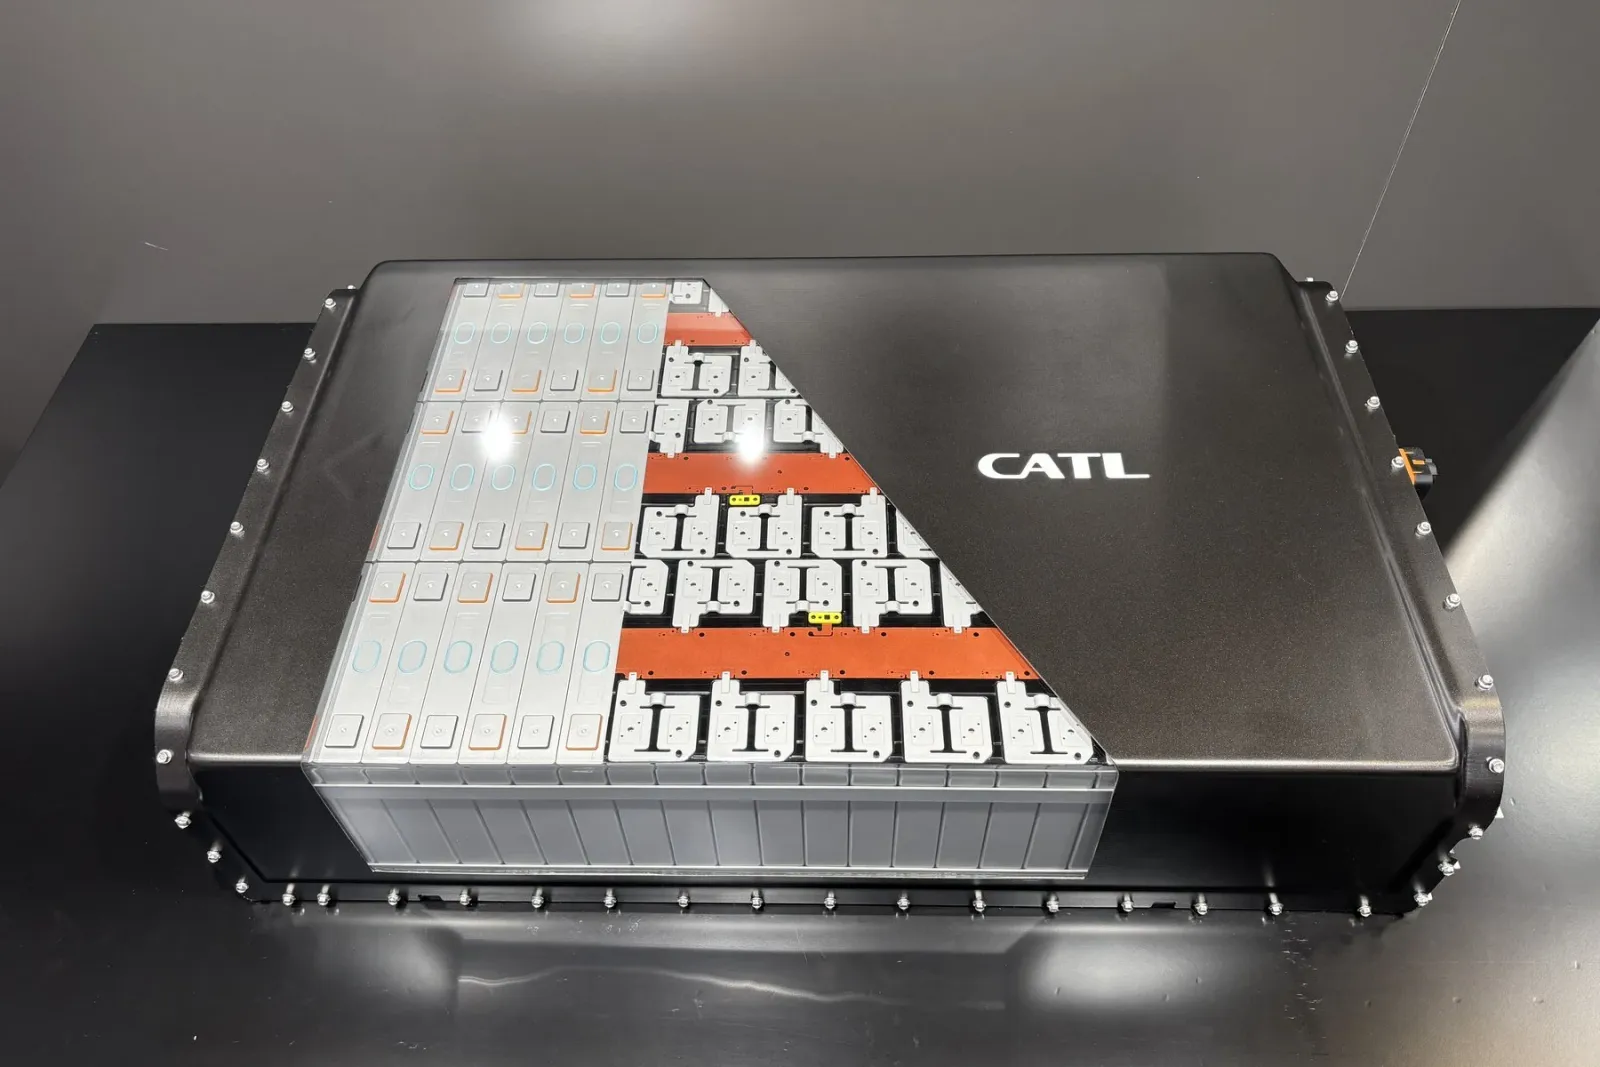
In the first nine months of the year, Chinese manufacturers captured more than half of the battery market for electric and hybrid vehicles outside of China. Korean and Japanese suppliers are all losing ground. This is according to a new analysis by SNE Research.
Image: Cora Werwitzke
The Korean market research firm SNE Research has analyzed the dynamics and share distribution in the electric vehicle battery market outside of China. The main finding is that the total capacity of these batteries rose to 426.7 GWh from January to September. Thus, the market grew by 24.7 percent compared to the same period last year. The clear beneficiaries are Chinese battery manufacturers.
"CATL, BYD, Gotion High-Tech, Svolt, CALB, and Eve Energy together captured 56.4 percent of this overseas market, representing an increase of over 13.3 percentage points compared to the previous year," writes SNE Research. CATL and BYD alone account for 44.5 percent of the market. In the corresponding period of 2025, this figure was 36.7 percent.
SNE Research specifically examined the sales of batteries for electric vehicles, plug-in hybrids, and other hybrids. Demand has varied regionally. Korean analysts note that demand in Europe and Asia was able to offset the persistent weakness in North America. Interestingly, China itself seems to be struggling as well. While SNE Research reports 24.7% growth for the global market, the increase when including China is only 19.7%. Thus, the People’s Republic is slowing down overall growth.
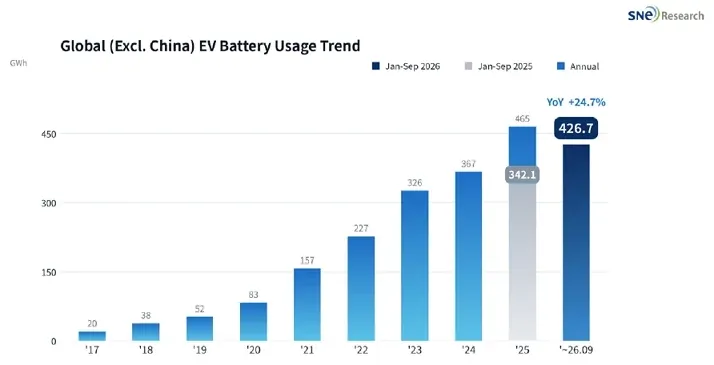
The following figures relate to the manufacturers themselves: The three Korean manufacturers, LG Energy Solution, SK On, and Samsung SDI, contributed 113.0 GWh globally (excluding China) from January to September — a 13.5 percent decline compared to the same period last year. Their combined market share dropped by 11.7 percentage points, from 38.2 percent to 26.5 percent. According to SNE Research, business performance declined sharply in North America, where the installed battery capacity of these three companies nearly halved, from 56.1 GWh to 28.1 GWh. In contrast, there was a slight improvement in Europe (from 58.7 GWh to 63.0 GWh) and in Asia as well (from 13.1 GWh to 17.5 GWh).
But one step at a time. After the first nine months, CATL once again leads the rankings. The company achieved a production volume of 143.7 GWh outside of China, accounting for exactly one-third of the market. Compared to the previous year, CATL’s output increased by 47 percent. Its market share rose by 5.1 percentage points to 33.7 percent. According to SNE Research data for Europe, production increased by 35 percent, from 71.5 GWh to 96.8 GWh, while in Asia the volume doubled to 27.1 GWh.
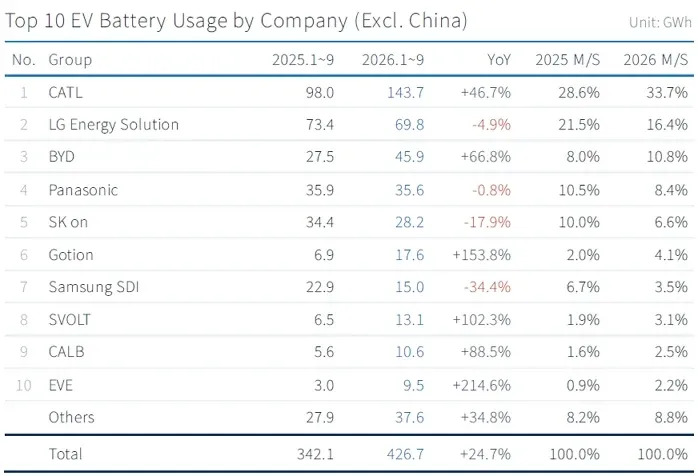
According to the analysts, LG Energy Solution holds second place with 69.8 GWh, a decrease of 4.9% year-on-year. The business in Europe and Asia showed positive growth. In Europe, it increased by 13% to 38.6 GWh, while in Asia it rose by 49% to 11.1 GWh. However, this could not offset the sharp decline in North America, which dropped by 45% year-on-year from 29.9 GWh to 16.5 GWh. As the overall market size expanded, LGES’s market share declined significantly by 5.1 percentage points, from 21.5% to 16.4%.
Next is BYD, which ranks third with 45.9 GWh, an increase of 67% year-on-year. The company’s market share grew from 8.0% to 10.8%. According to SNE Research, this growth was distributed across Europe (17.4 GWh, +67% year-on-year), Asia (14.8 GWh, +41% year-on-year), and South America (7.1 GWh, +136% year-on-year).
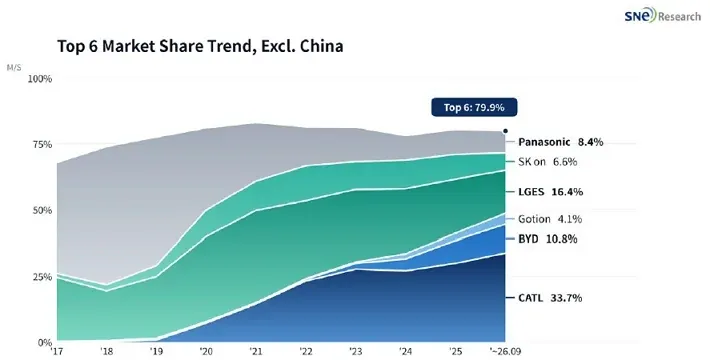
Panasonic ranks fourth in the rankings with 35.6 GWh for the first nine months of the year, a decrease of 0.8% year-on-year. “Although deliveries to Tesla in North America supported the results, growth remained significantly behind market developments outside of China,” the authors comment. Panasonic’s market share dropped by 2.1 percentage points to 8.4%. Looking back further, Panasonic’s example clearly shows how much the market has changed over the past few years:
SK Onauf, ranked fifth, suffered significant losses, with its production volume dropping to 28.2 GWh (-18% year-on-year). Its market share declined accordingly from 10.0% to 6.6%. “The company supplies batteries to companies such as Hyundai Motor Group, Ford, Volkswagen, and Mercedes-Benz. Nevertheless, its usage in North America fell by 46.7%, and in Europe by 2.2%,” states the study.
Gotion, a partner of Volkswagen, saw its production increase by 153.8% to 17.6 GWh, overtaking Samsung SDI, which dropped to seventh place. Samsung SDI recorded only 15.0 GWh (-34.4% year-on-year), the steepest decline among the top 10 companies. Its market share fell from 6.7% to 3.5%. While sales in Europe remained at 9.4 GWh, matching the previous year, Samsung SDI suffered a severe downturn in North America, with sales dropping by 66% year-on-year from 12.0 GWh to 4.1 GWh.
Three second-tier Chinese manufacturers make it into the top 10 — specifically SVOLT, CALB, and EVE Energy. SVOLT saw growth of 102 percent to 13.1 GWh, CALB grew by 88.5 percent to 10.6 GWh, while EVE Energy achieved an impressive increase of 215 percent to 9.5 GWh.
In summary, it can be concluded that the three Korean manufacturers along with Panasonic had to cede market share to exclusive Chinese players in the global market, while the six mentioned Chinese companies consistently and rapidly expanded their presence in Europe. A key factor here is cell chemistry: “The 11.9 percentage point increase in LFP’s share of the market outside China, from 15.8% to 27.7%, reflects the same trend,” emphasize the analysts. This is because it is primarily Chinese manufacturers leading the way in LFP technology. Especially in Europe, the adoption of LFP is on the rise—“particularly in entry-level models, making price competitiveness a crucial criterion in supplier selection,” comments SNE Research.
The analysts also provide an outlook based on the data: in their view, regional political conditions and the diversification of demand will primarily determine the competitiveness of suppliers. As a result, some manufacturers are now shifting more toward batteries for stationary storage to achieve greater diversification, especially in North America. Regarding Europe, the analysts consider factors such as the automotive package and the resulting appeal of phasing out internal combustion engines, along with potential “Made-in-Europe” rules, to be key influencing factors.