
NIO reported its third consecutive profitable quarter. Margins remain stable, while costs continue to decline.
On September 1, NIO released its results for Q2 2026, showing a positive Non-GAAP profit for the third consecutive quarter. The company reported a Non-GAAP net profit of 26 million RMB and a Non-GAAP operating profit of 207 million RMB, on revenue of 32.14 billion RMB. For the market, what matters more than just “did it lose again?” is whether NIO can maintain its margins and scale up its operations.
In Q2, the Chinese automaker delivered 107,658 vehicles, representing a year-on-year increase of 49.4% and a quarter-on-quarter rise of 29%. Revenue from vehicle sales climbed to 29.06 billion RMB, an increase of 80.1% year-on-year. The profit margin on vehicles was 18.5%, only 0.3 percentage points lower than in Q1 but 8.2 percentage points higher than a year earlier. This is already a level that many young EV brands in China have yet to reach, as many of them remain below 15%.
ONVO is growing faster than NIO and reshaping its sales structure
In Q2, NIO’s main brand accounted for 60,945 vehicles, ONVO for 29,124, and Firefly for 17,589. Their respective shares were 56.6%, 27.1%, and 16.3%. In the previous quarter, these figures were 70.1%, 16.0%, and 13.9%.
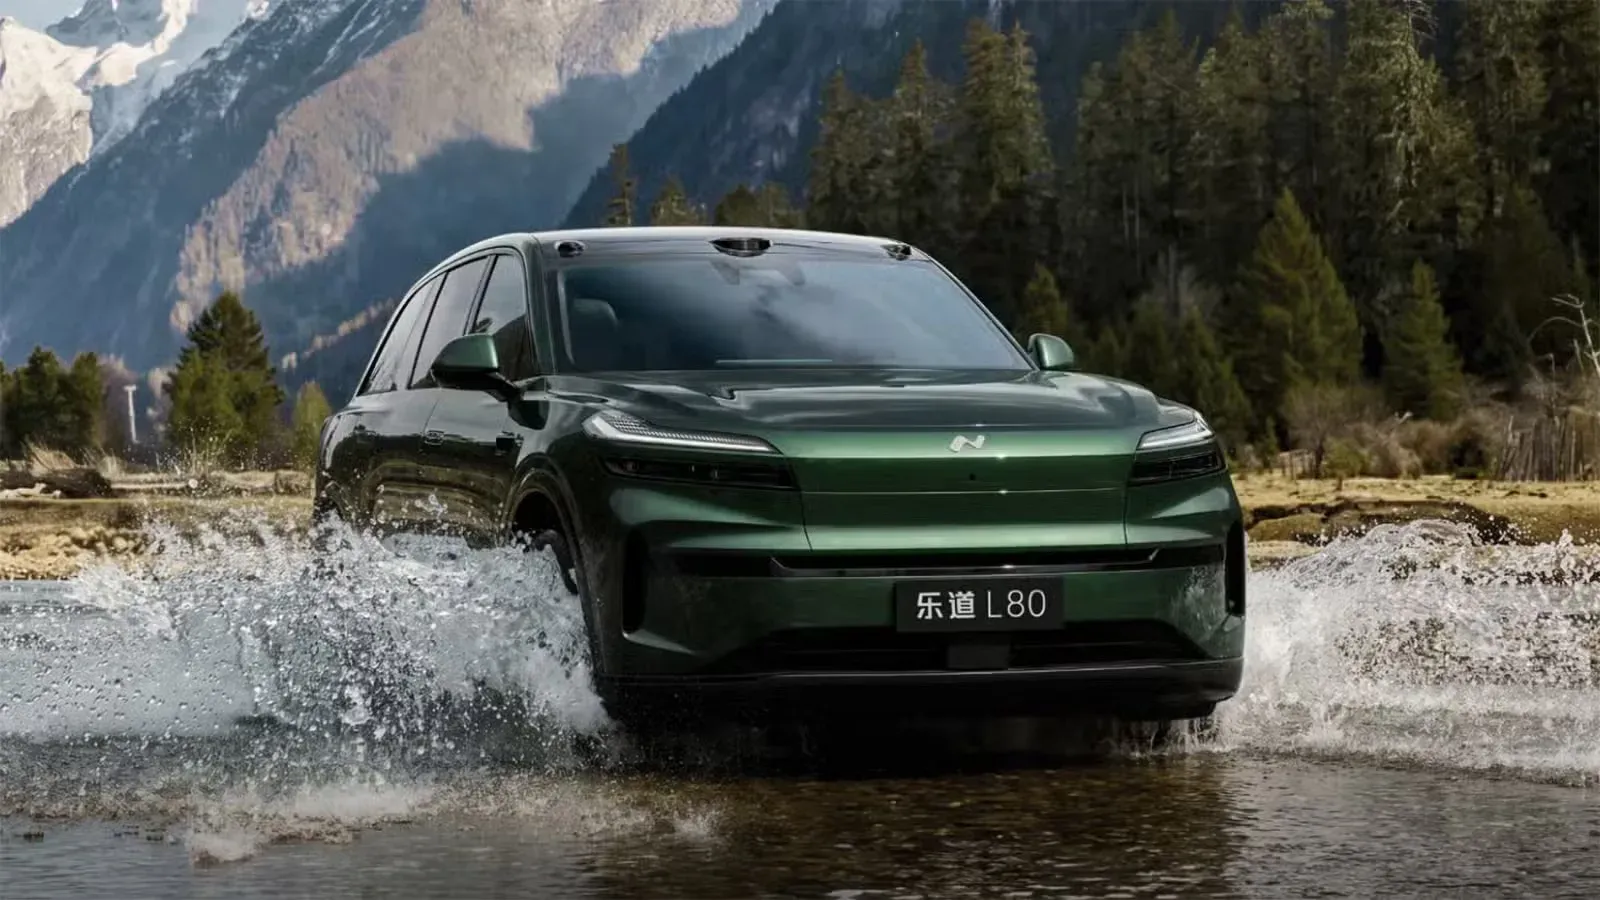
The change is evident. ONVO is growing rapidly, and along with it, the sales mix is changing. This usually puts pressure on margins because NIO’s main brand commands higher prices. Meanwhile, the margin decline was minimal. This suggests that ONVO, especially the L80 and L90 models, is generating higher profits than expected.
The problem lies elsewhere. Despite a positive Non-GAAP result, the company still incurred an operating loss of 347 million RMB under GAAP and a net loss of 528 million RMB under GAAP. In short, the vehicles are starting to generate profits, but the organization still costs too much.
R&D and sales are growing too fast, with Q3 showing no sign of a surge
Research and development expenses amounted to 2.14 billion RMB in Q2, representing a year-on-year decrease of 28.7% but an increase of 13.8% quarter-on-quarter. Sales, general, and administrative costs rose even more sharply. SG&A reached 4.425 billion RMB, up 11.6% year-on-year and 26.5% quarter-on-quarter. This outpaced the quarterly growth in total revenue, which was 25.9%. Not good.
Add to this the issue of raw materials. Stanley Qu said that compared to the end of 2025, the cost per car has increased by about 14,000 RMB, with another increase of 2,000–3,000 RMB per car expected in the second half of the year. The target margin for Q3 and Q4 is at a level “roughly consistent with Q2,” around 18%.
The forecast for Q3 is cautious. NIO aims for 108,000–111,000 deliveries and revenue of 33.285–34.051 billion RMB. This represents only a 0.3–3.1 percent increase in vehicles compared to Q2 and a 3.6–6.0 percent rise in revenue. Without new models this quarter, the company relies more on a better product mix and more efficient cost cuts rather than a surge in volume.
William Li added a second, more product-focused point. By 2027, NIO plans to refresh the “5566” lineup, while ONVO will receive a new model of “strategic-level” importance. It was not explicitly stated whether this refers to the previously announced sedan. Firefly is set to remain a single-model brand. Li compared its positioning to that of the iPhone, meaning special editions and updates rather than expanding the product range. He also noted that ONVO’s recognition is currently roughly where NIO was 5–6 years ago. The company aims to improve this through integrated stores, marketing efforts, and family-oriented offerings.
On paper, NIO has already entered the stage of reaping rewards. The question isn’t whether it can sell 100,000 cars per quarter, but rather whether it can reach 150,000–200,000 without its battery swap network and three-brand strategy becoming a hindrance again. What do you think—will ONVO drive this growth, or is it too early for such optimism?
LovEV Newsletter
Want more content like this?
Sign up—we’ll send you a weekly summary once the newsletter starts.