
GreenWay remains the leader in fast charging with over 20% market share. Lidl and Powerdot are closing in rapidly
In short:
- GreenWay controls 20.5% of the market for public fast charging stations.
- Lidl has increased its share to 17.5%, while Powerdot ranks third with 15.3%.
- GreenWay plans to add over 20 more charging hubs with up to 400 kW capacity by 2026.
GreenWay feels the pressure from competitors
The market for public charging stations in Poland is growing so rapidly that the positions of the largest operators can change within just a few months. GreenWay remains the leader in the fast charging segment, but its advantage over competitors has significantly narrowed.
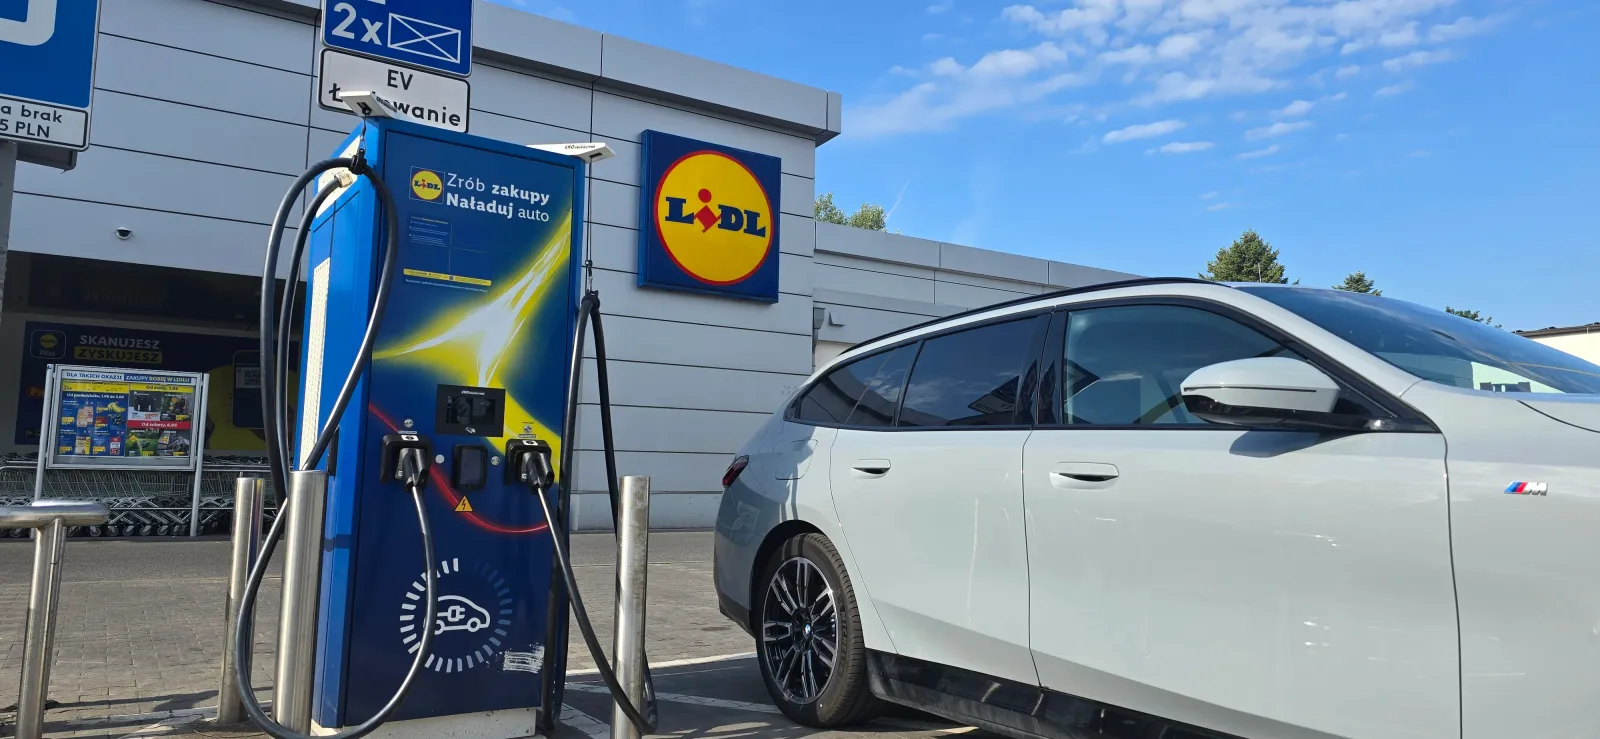
According to F5A New Mobility Research and Consulting, as of the end of Q3 2026, GreenWay held a 20.5% market share in publicly available DC charging stations. Lidl Polska came in second with 17.5%, followed by Powerdot at 15.3%.
The gap widens significantly thereafter. Orlen Charge accounts for 7.5% of the market, Kaufland for 5.6%, while Tesla and Moya Energia each hold 3.4%.
Lidl Closening in on GreenWay
What’s most interesting isn’t just the order but the pace of change. In Q2, GreenWay had a 21% market share, Lidl 16.4%, and Powerdot 16.1%. Three months later, the leader’s share dropped by 0.5 percentage points, while Lidl gained 1.1 percentage points. Powerdot, on the other hand, lost 0.8 percentage points.
This means GreenWay’s lead over Lidl narrowed to 3 percentage points. At the end of the first quarter, the situation was different: GreenWay held 20.5%, while Lidl and Powerdot each had 16.5%.
The biggest increase in the third quarter, alongside Lidl, was seen by Moya Energia, which raised its share by 1 percentage point. Tesla gained 0.6 percentage points.
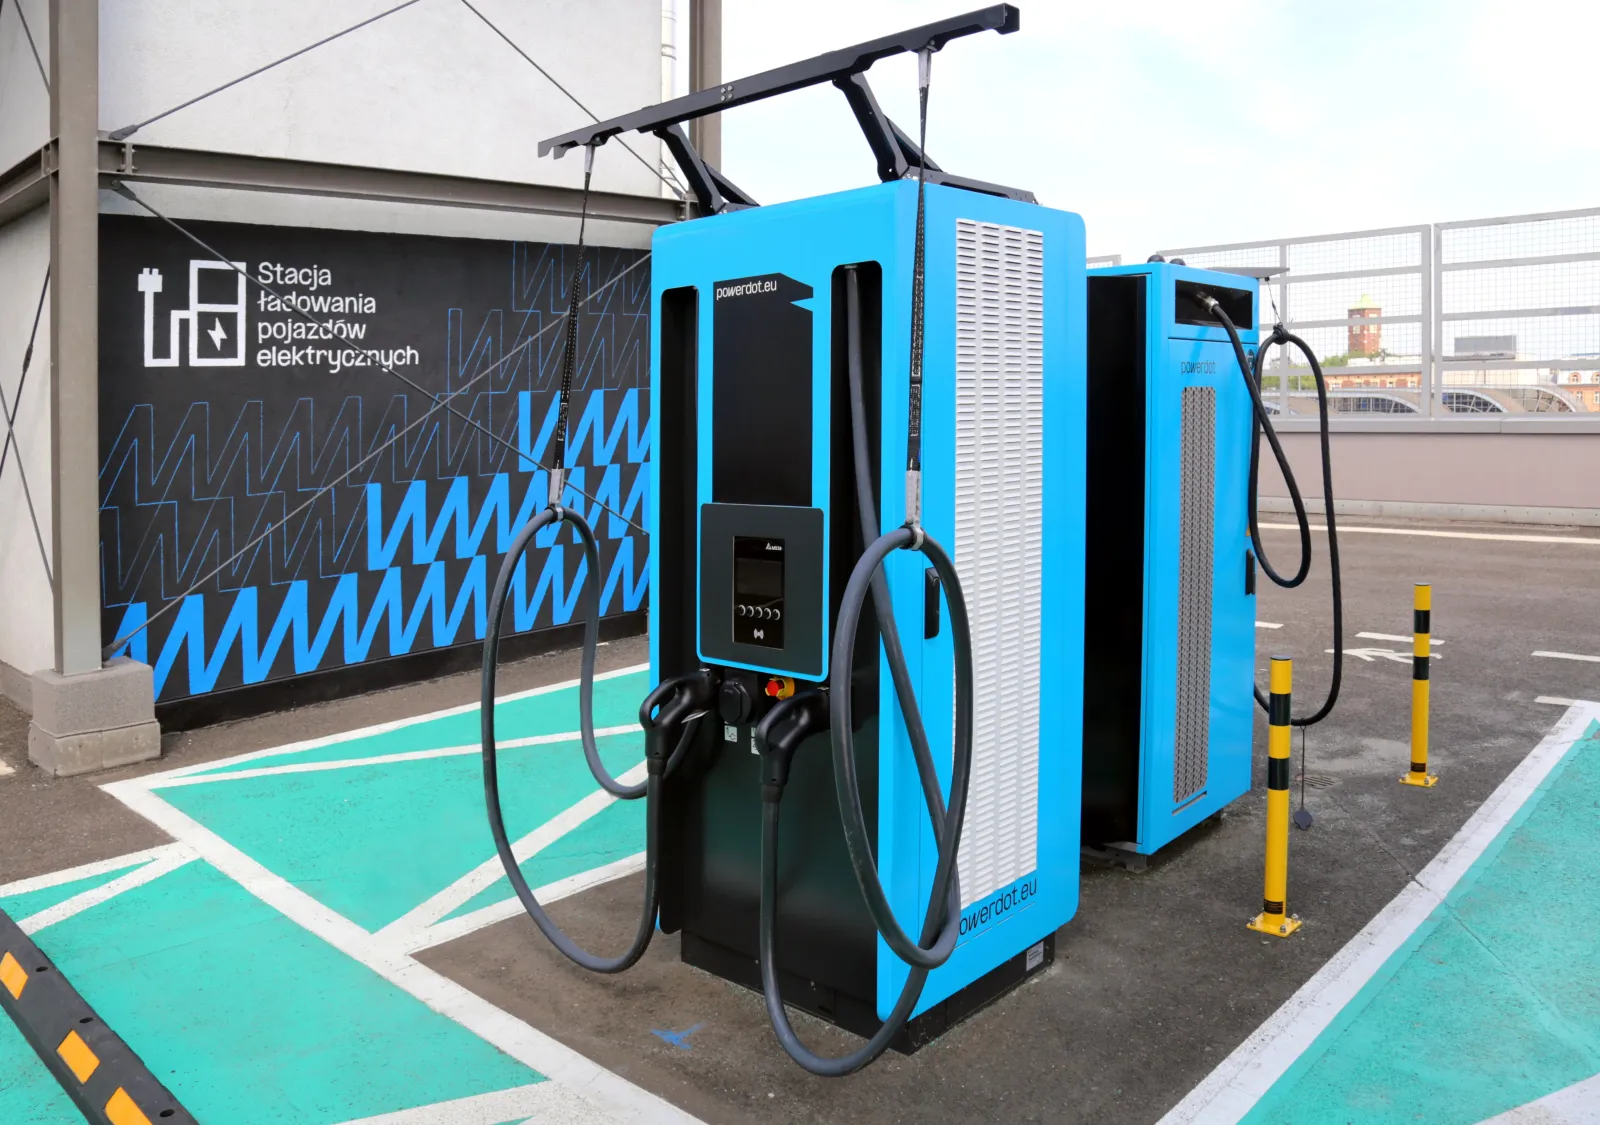
The ranking of the top fast charging network operators at the end of September was as follows:
GreenWay Polska – 20.5%
Lidl Polska – 17.5%
Powerdot – 15.3%
Orlen Charge – 7.5%
Kaufland – 5.6%
Tesla – 3.4%
Moya Energia – 3.4%
Elocity – 3.2%
Budimex Mobility – 1.8%
Polenergia – 1.7%
There are already over 13,900 public charging points in Poland
The growing share of the largest operators needs to be compared with the overall market development rate. According to the Polish Association for New Mobility (PSNM), as of the end of September, there were 13,936 publicly accessible charging points in Poland. Of these, 7,113, or 51%, were fast charging points using direct current, allowing for quicker vehicle charging. At the end of March, there were only 5,980 such points. Thus, their number increased by over 1,100 in just half a year.
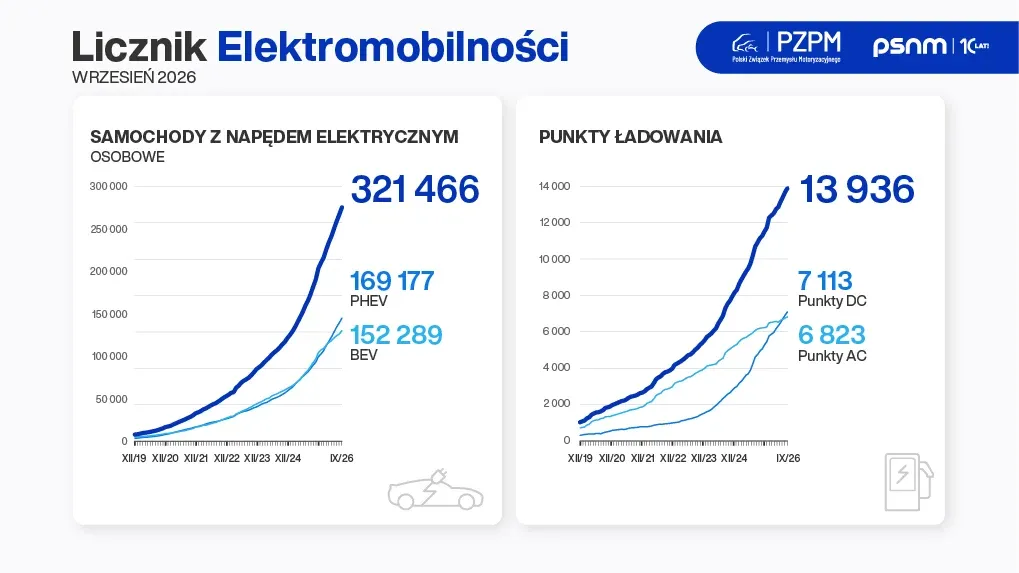
Thus, significant changes can be seen in the market. Just a few years ago, public infrastructure relied heavily on AC devices with relatively low power output. Today, operators are investing much more in fast and ultra-fast charging stations along roads, shopping malls, and stores.
GreenWay is preparing over 20 new hubs
GreenWay isn’t planning to hand over the lead easily. The operator has just announced another phase of developing its infrastructure.
By the end of 2026, over 20 new ultra-fast charging hubs are set to be launched in Poland. According to the map released by the company, new locations will appear in various parts of the country, with the charging devices offering power levels up to 400 kW.
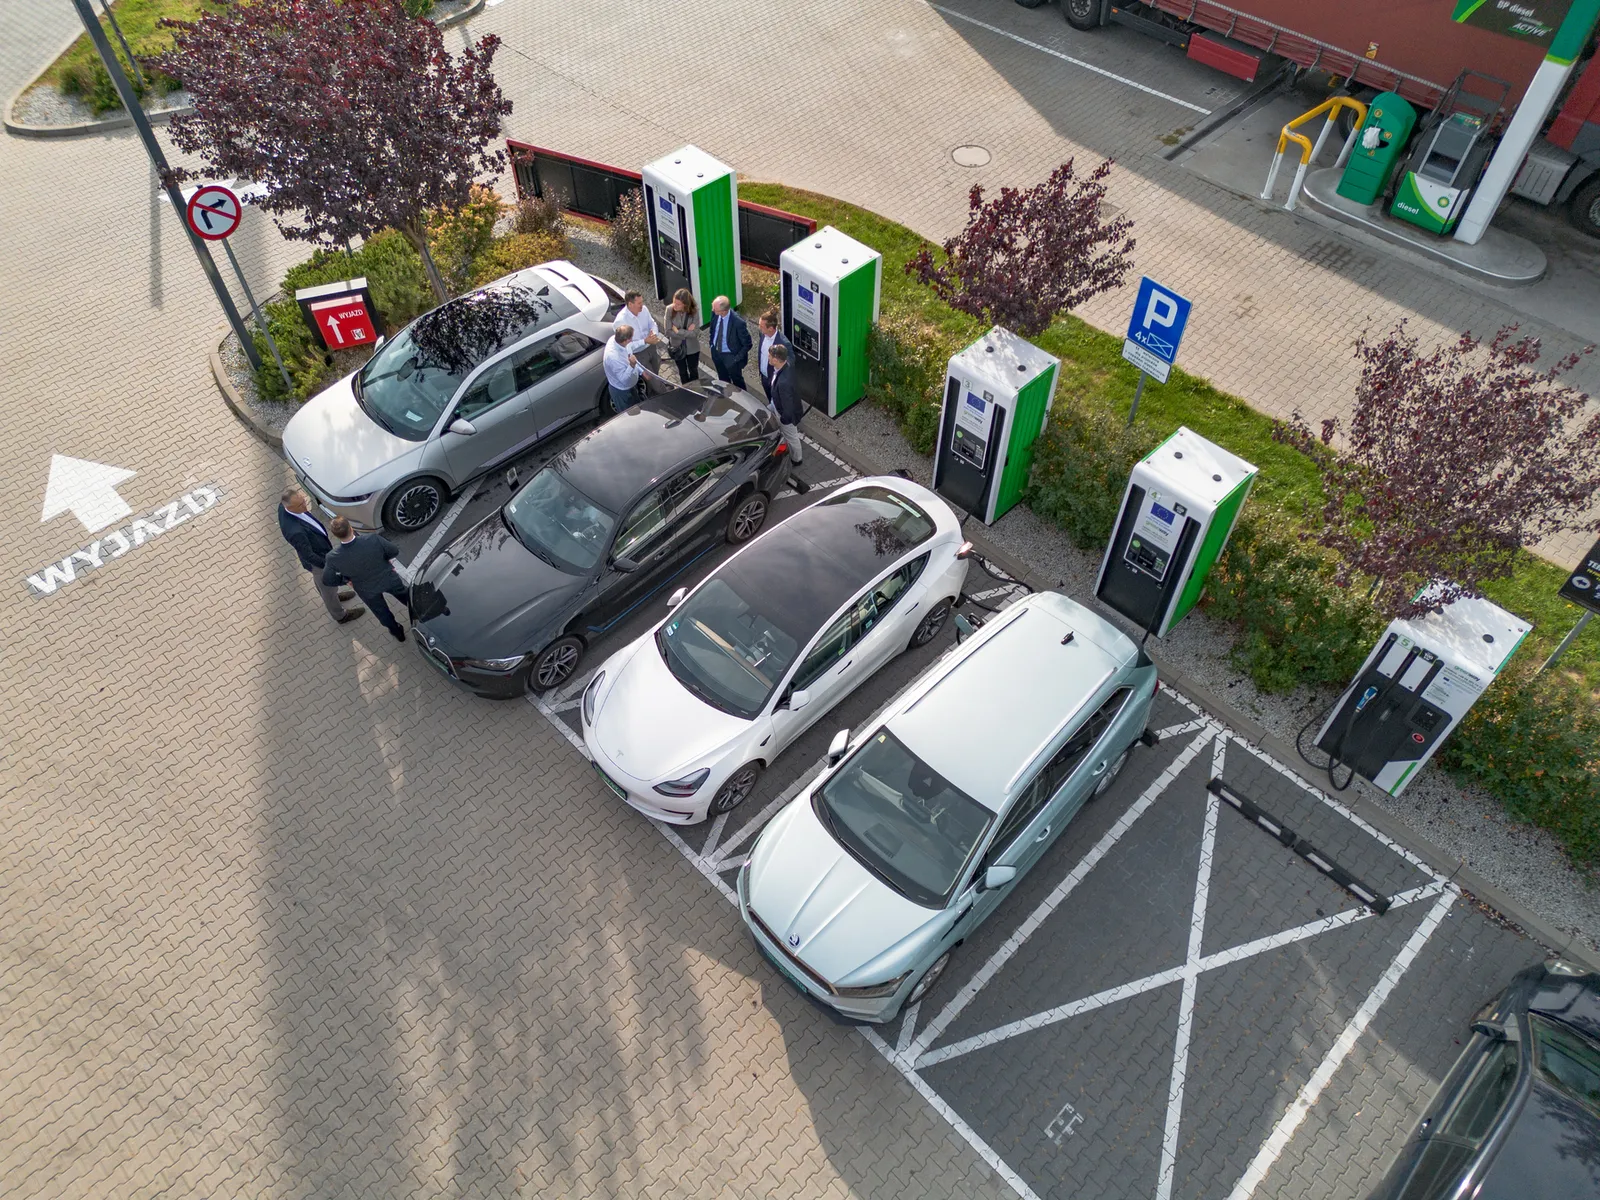
The company is increasingly moving away from the single fast charger model in favor of larger locations with multiple charging stations. This is particularly important for routes where not only the maximum power of the device matters but also the number of cars that can charge simultaneously.
The expansion has been ongoing since the beginning of the year. In the first half of 2026, GreenWay opened 81 own charging stations with a total capacity of 10.4 MW, the vast majority of which were located in Poland. During this time, the number of locations increased by 9%, the number of charging stations by 8%, and the total capacity of the infrastructure by 11%.
Even earlier, the operator completed a project involving 35 ultra-fast hubs and 253 new DC charging stations with capacities up to 400 kW.
Orlen leads in AC charging
GreenWay is not the leader in the second part of this market. For AC charging stations, which are mainly used during longer stops, Orlen Charge held the top position at the end of the third quarter with a 13% share.
GreenWay was right behind it. The detailed F5A ranking shows a 12.5% share. Following are Elocity with 8.3%, Eleport at 6.2%, and Noxo at 6.1%.
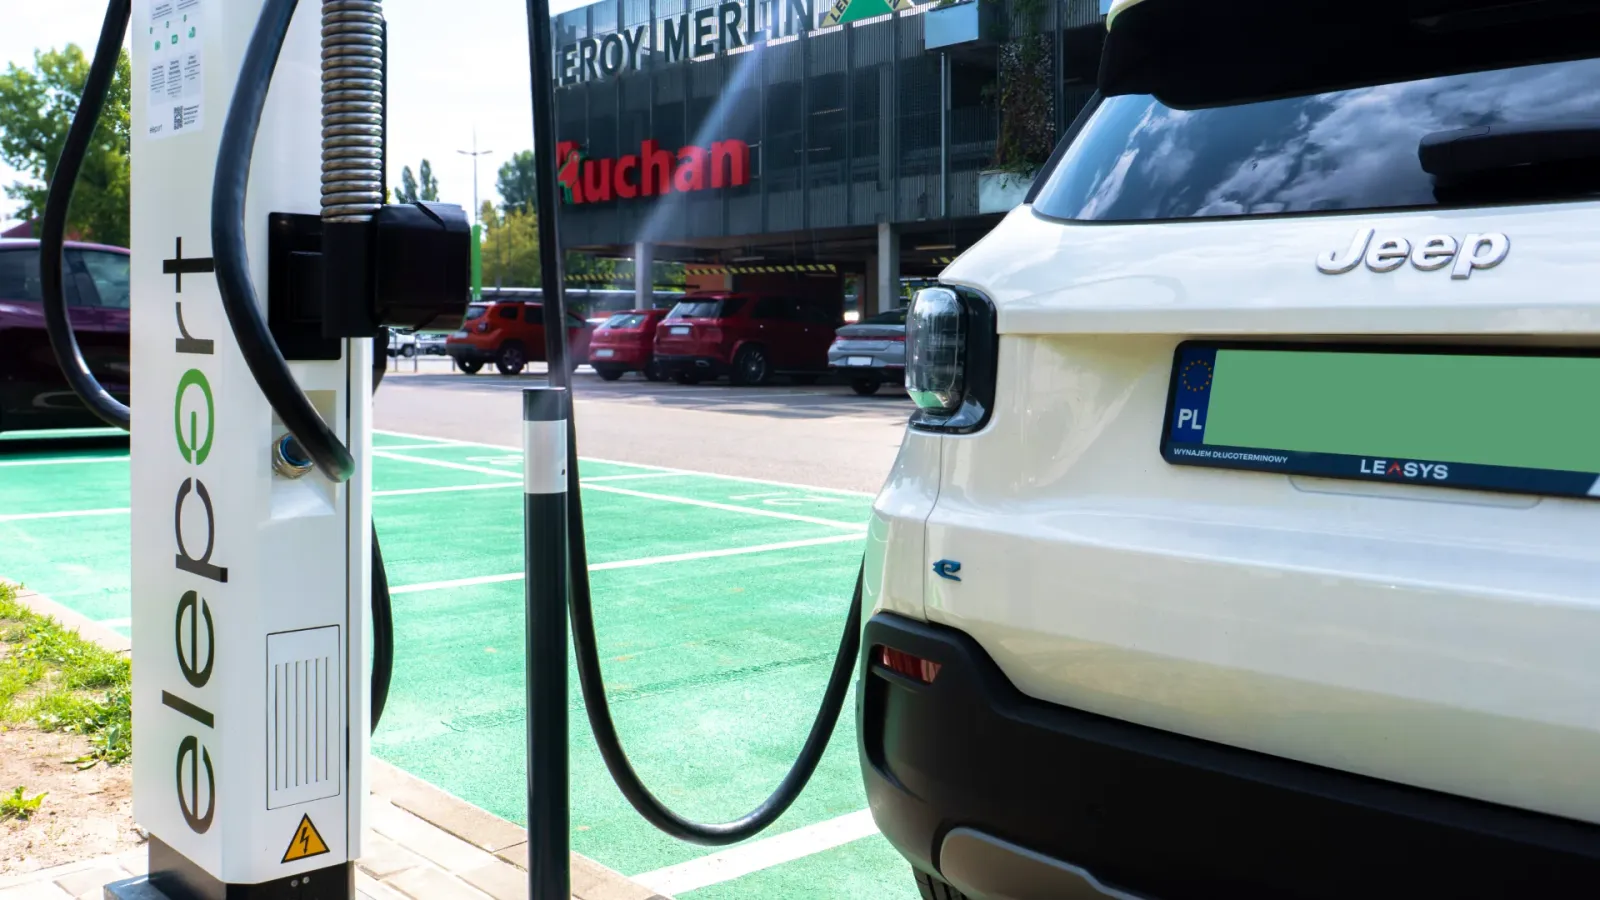
The differences are therefore small, but the direction of change is clear. At the end of 2025, GreenWay also led in the AC segment. By the end of the first quarter of 2026, Orlen held 13.2%, compared to GreenWay’s 13.1%, while both operators had 12.9% after the first half of the year. The third quarter thus brought a more pronounced separation in their positions.
The market is becoming increasingly competitive
However, the most significant change isn’t just the swapping of individual positions in the rankings. Poland’s charging infrastructure is entering a phase where several large networks operating under different models are competing for drivers.
GreenWay is expanding its traditional nationwide network along with increasingly larger hubs. Lidl and Kaufland leverage their vast network of stores and parking lots. Powerdot focuses primarily on locations near shopping and service centers. Orlen can rely on its existing network of gas stations, while Tesla is increasingly making its Superchargers available to drivers of other brands.
As of the end of the third quarter, GreenWay still holds a clear lead in fast charging, but the gap between first and third place is now only 5.2 percentage points. Lidl is closing the gap particularly quickly.
GreenWay’s response is to make further investments in large and strategic locations. Over 20 new hubs planned for this year alone could help the operator maintain its leading position. Meanwhile, the pace of expansion by competitors suggests that the race to become Poland’s largest fast-charging network will become increasingly competitive.
Piotr Sobczyk