
“The growth potential is enormous”: ChargePoint’s Europe head John Saffrett in an interview
John Saffrett has only been with ChargePoint as EVP and Managing Director Europe for a few weeks, but he already understands the challenges of electric mobility from a different perspective very well: As Global Deputy CEO of vehicle management and leasing company Ayvens, he previously oversaw operations in 42 countries with around 3.5 million vehicles, including more than half a million electric cars.
In his new role, Saffrett aims to help the U.S. company ChargePoint become a leader in Europe, both in hardware and software. He sees the charging industry facing structural changes: investors are increasingly demanding profitable business models, access to capital is becoming more selective, and not all providers will be able to sustain themselves in the long term. Therefore, Saffrett expects market consolidation over the next three to five years.
At the same time, the ChargePoint executive sees enormous growth potential, as although battery electric vehicles already account for more than one-fifth of new registrations in some European markets, their share of the total vehicle fleet remains below five percent. In an interview with electrive, Saffrett explains ChargePoint’s strategy, discusses competition with Chinese hardware suppliers, the importance of reliable charging solutions for fleets, and the opportunities emerging in the truck charging sector. Here we go:
Mr. Saffrett, you have only been with ChargePoint for a few weeks. How was your start?
> He was great. I had previously been a member of ChargePoint’s board, so I was already familiar with the company. While I wouldn’t say I knew every detail, I had a good understanding of where the company stood at that time and the challenges it faced.
>
>
>
> Europe is becoming increasingly important for ChargePoint’s global success. We even moved up my start date by a week so I could attend the icnc in Berlin. It would have been a missed opportunity not to participate in an event that brings together so many of the key players in Europe’s charging infrastructure sector.
>
>
I spent time with the team and met with clients. I probably walked around the event venue 20 times, got to know the various stakeholders, analyzed their activities, and then asked our team: How do we compare? Are we competing with them? Where do we encounter them in the market? It were very informative first days.
Why did you choose ChargePoint? Your professional background is more in fleet management and vehicle leasing, right?
I worked at Ayven as Global Deputy CEO. We were active in fleet management, vehicle leasing, and vehicle maintenance across 42 countries, managing a fleet of around 3.5 million vehicles. Additionally, we operated one of the world’s largest cross-brand fleets of battery electric vehicles, with over half a million electric cars. This gave us excellent insight into the challenges surrounding charging — from customers’ initial concerns about switching to electric vehicles to developing solutions to address those specific worries.
We therefore had a very good understanding of how charging and mobility infrastructure were evolving and where the real challenges lay.
> After nearly 29 years in this industry — interrupted only by a brief stint in the banking sector — I felt it was the right time to change perspectives.
According to your experience, what are the biggest hurdles for fleet managers who want to switch to electric vehicles? Is it the vehicle itself, or is charging still the main problem?
> Much of it remains psychological. Concerns about range are usually the first issue raised.
> However, since many new electric vehicles now offer ranges of about 400 to 500 kilometers, this concern is gradually decreasing. The situation is different for delivery fleets, as they follow different schedules; but for typical business car drivers, the next questions are: Where and how can I charge?
>
>
> People often worry about public charging, even though a large portion of the charging actually takes place at home. What’s more crucial is whether a good charging solution can be provided at home, in the office, or at the workplace.
>
>
> Additionally, there is uncertainty regarding subsidies and taxation. Incentives are introduced or removed, thresholds change, and vehicle prices fluctuate. This makes fleet planning difficult.
> For example, a company may want to assure 500 employees at a certain hierarchical level that, “You can use this vehicle at these costs for the next three years.” If a subsidy is suddenly removed or a threshold changes, the vehicle may no longer meet the current regulations.
>
>
> One must therefore clarify all these aspects before a company can finally say, “Okay, now we can switch to electric mobility — and do so strategically.”
Does the charging capacity of the vehicles themselves also play a role?
> That was definitely an issue, especially with older generations of electric vehicles. Although a lot has been invested in high-capacity charging infrastructure, not every vehicle on the road can actually utilize the available charging power.
>
>
> Vehicles that were considered highly advanced just a few years ago may have significantly lower charging capacity compared to today’s models. This becomes particularly relevant when these older electric cars make their way onto the used car market.
>
>
> While the latest generation of vehicles addresses many of these issues, there is still a substantial number of older electric cars in Europe that cannot fully benefit from improvements in charging infrastructure.
How do you assess Europe’s charging ecosystem today?
> It is highly fragmented. I expect significant consolidation in the next three to five years. The era when technology companies could operate for extended periods without delivering financial returns to investors is coming to an end, especially as the industry reaches a maturity level comparable to established sectors.
> There is increasing pressure on companies to prove they have a profitable and sustainable business model. At the same time, access to investment capital is becoming more selective.
>
>
> Therefore, I assume that a number of players—provided they have long-term viable products and technologies—will seek acquisitions, mergers, or strategic partnerships.
>
>
> Unfortunately, some companies will not be able to present a long-term viable strategy or simply lack competitiveness. I wouldn’t say the charging infrastructure industry is already mature; however, we have moved past the stage where two people in a room can develop something that suddenly takes off and build a company around it. For example, major CPOs are increasingly willing to collaborate with partners they believe will remain strong in three, five, or ten years. This will inevitably lead to consolidation.
Which European markets do you consider leading in the charging infrastructure sector currently?
The Benelux countries and the Nordic countries have traditionally been leaders in terms of the maturity of their overall infrastructure. Both regions benefited from strong and, above all, consistent government support. The policies were maintained over time rather than being revised due to industry pressure or an economic downturn. Germany, the United Kingdom, and France are now catching up. A significant part of Southern Europe has not yet undergone the same transformation. Spain, Italy, and Portugal are beginning to move forward, and I think Eastern Europe could also trigger a very strong wave once it’s time.
What could drive this development in Eastern Europe?
> I think the charging infrastructure for trucks could be an important driver. As EU regulations accelerate the introduction of electric trucks, electrifying key freight routes and the TEN-T core network will require extensive charging infrastructure. This infrastructure can then have a domino effect on the entire charging ecosystem in these markets.
Which markets are currently a priority for ChargePoint in Europe?
> The DACH region is very important to us. Our other key markets include the UK and France. We are also active in other European markets, such as Southern Europe and the Benelux countries.
What are your main goals in your new role?
> I come from a market leader company and am convinced that ChargePoint has the opportunity to become a leader in Europe as well, both in hardware and software.
>
>
> > To succeed in an industry, one must strive for market leadership. Of course, there are many very strong competitors, especially in the hardware sector. However, I am convinced that the next generation of hardware we bring to the European market is ideally suited for Europe in terms of size, adaptability, and quality.
>
>
> Utilization and reliability are becoming increasingly important, with availability needing to be nearly 100 percent. My goal is therefore to make ChargePoint a leading yet responsible market leader. I don’t want us to gain market share at any cost. That only leads to destructive competition, and I don’t think it’s good for the industry.
>
>
> I am also convinced that ChargePoint can play a significant role in supporting and shaping the charging infrastructure industry in Europe. I believe we haven’t been present enough in this discussion so far. This is one of the reasons for my appointment and my position on ChargePoint’s leadership team.
How large do you still estimate the growth potential in Europe to be?
> It’s enormous. We often talk about battery electric vehicles accounting for more than 20 percent of new registrations in some markets. However, when looking at the overall vehicle fleet, the share of BEVs is still below five percent.
>
>
> Therefore, there is still huge growth potential over the next five to ten years. If charging infrastructure providers are already achieving satisfactory utilization rates today, imagine what will happen when the share of electric vehicles in the total fleet rises from five to ten, 15, or 20 percent.
>
>
> This highlights the multiplier effect on the charging infrastructure required for these vehicles. There is a tremendous market opportunity here. I wouldn’t have joined ChargePoint if I wasn’t convinced that we can succeed in this market.
ChargePoint is known in Europe for its software business, especially be.ENERGISED. What role will hardware play alongside software in your European strategy?
> We are active in both software and hardware businesses. We sell charging hardware, combine our hardware with our own software, and also offer our software platform for third-party hardware. be.ENERGISED is a highly powerful charging management platform. We intend to continue investing in it and strengthening it, as we believe it can achieve even greater success with the right focus and maintain its market leadership.
>
>
> We also have our partnership with Eaton, which has proven very successful in the USA, and we want to expand it further in Europe. Many charging stations first require additional electrical infrastructure and capacity — and that is exactly Eaton’s core business. This creates a strong combination.
I'm a bit skeptical about the hardware market. There are already numerous manufacturers of AC and DC chargers in Europe. Does the market really need another DC charger?
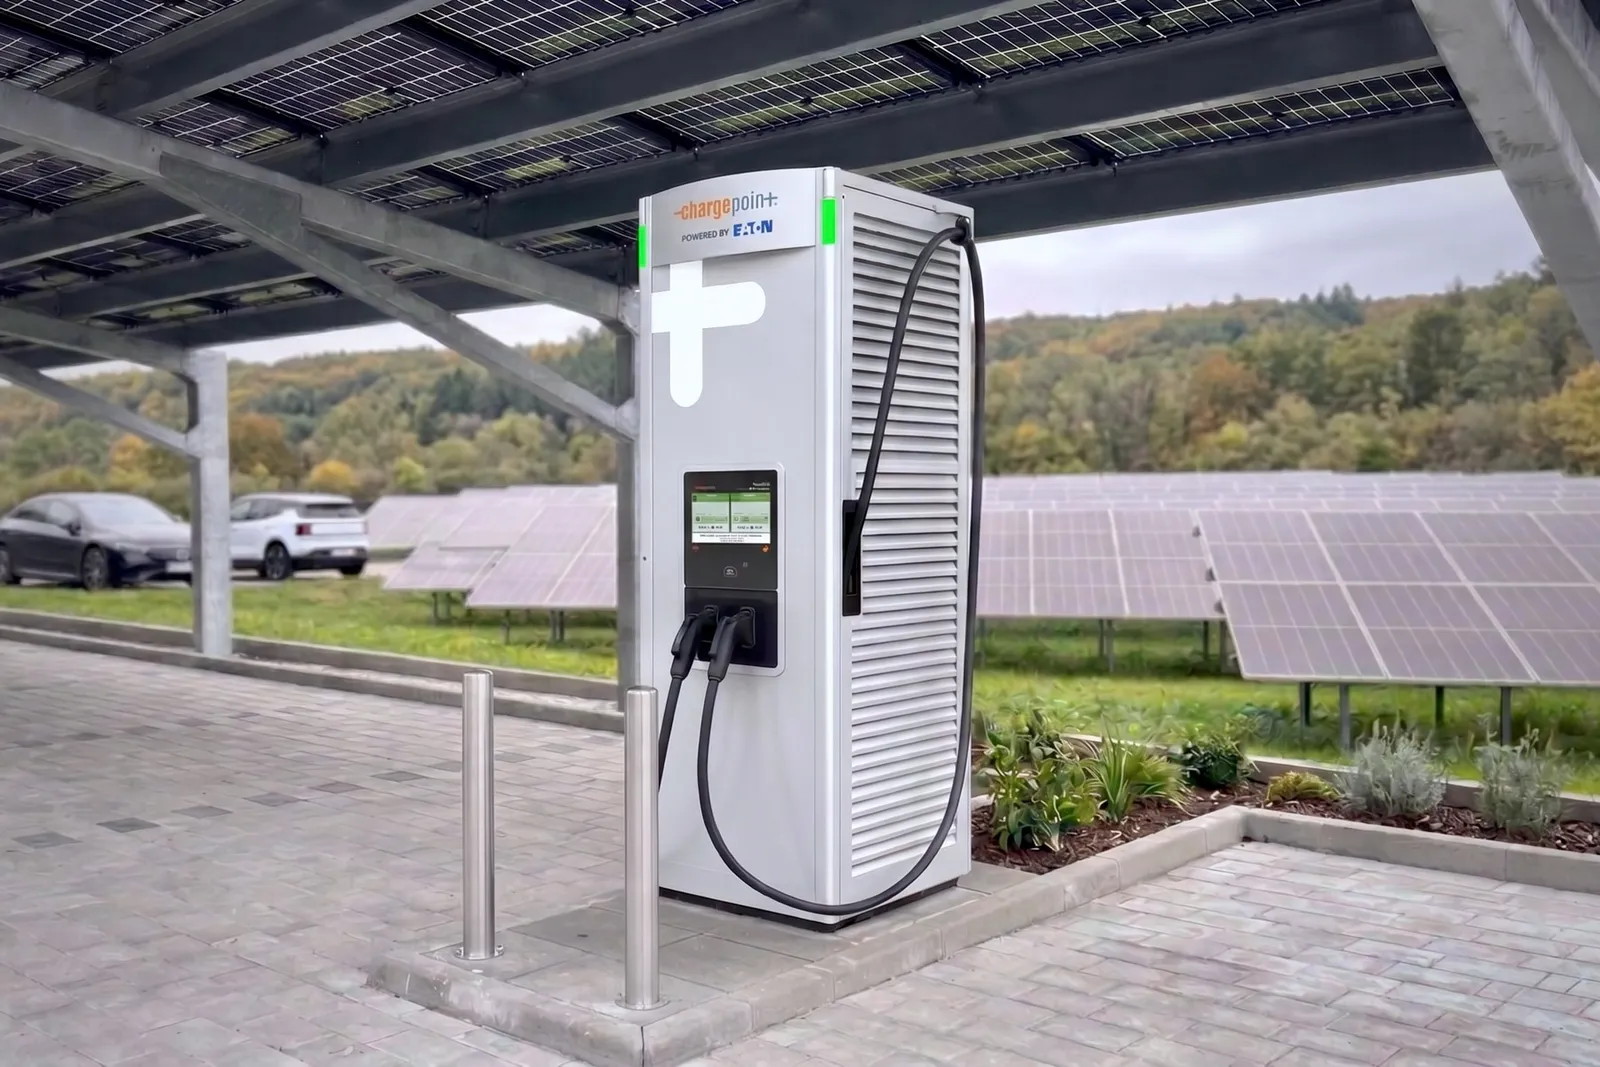
> Our new Express Solo DC charger combines top-tier technology in areas such as cooling and efficiency. It is also very compact and modular for its performance level.
>
>
> But we look beyond simply using the charger. The broader question is how to optimize charging infrastructure and what the total electrical capacity available at a location actually is. How can this capacity be managed, and how can the greatest possible portion of the available power be utilized effectively over a 24-hour period?
>
>
> The technology inside the charging station opens up the possibility for us to explore a range of additional use cases. These are areas we aim to bring to market over time.
Technology is one factor, and price is another. How can ChargePoint compete with Chinese hardware suppliers?
> We must continuously improve our production and procurement processes to ensure we remain competitive. As in any market, there is a relationship between price and quality. We need to find the optimal balance – the point where customers are willing to pay a premium for a product because it excels in terms of quality, reliability, durability, and associated support.
>
>
> However, the price differences that the market tolerates are relatively small. This sets the framework within which hardware can be priced competitively.
Is your hardware strategy focused primarily on passenger cars, or do you see opportunities in the truck charging sector as well?
> Both, though we see significant potential in the truck charging area.
> EU regulations are driving the introduction of electric trucks, and the expansion of charging infrastructure along the TEN-V core network will play a crucial role in this process.
>
>
> Charging at depots is also a key component of truck electrification. In such environments, availability must be nearly 100 percent. Large logistics fleets simply cannot afford to rely on unreliable charging infrastructure.
>
>
> Therefore, it is not enough to simply bring hardware to market. We need to build an ecosystem of services and support around it so that customers can trust that the systems provide the required availability. And this must be done correctly from the start.
>
>
> Logistics companies make far-reaching, long-term decisions regarding their infrastructure. If an installation is faulty or the support is inadequate, it spreads word among industry peers. This makes it significantly harder to acquire new customers. Therefore, we will spend considerable time optimizing the model before scaling it up.
Germany has very specific regulatory requirements, especially regarding calibration laws. How significant is this challenge for ChargePoint?
> All products we sell in Germany must comply with calibration laws or other relevant certification requirements.
> It is undoubtedly a challenge—but one that all players in this market must address.
Given your background: Should we assume that the fleet segment will become even more important for ChargePoint in Europe going forward?
> ChargePoint is already active in various segments, and the fleet business already constitutes an important part of our activities.
> Fleets for last-mile delivery, as well as truck and depot-based fleets, are clearly significant growth areas. Last-mile delivery has increased dramatically in Europe over the past decade; these fleets need to be electrified more and more to remain able to access cities. A similar trend is expected in the truck sector.
>
>
> We are already well-established in the automotive and fleet sector — so I’m not joining the company to explore this market from scratch. We already have strong partnerships with OEMs, including Mercedes and Ford Pro.
>
>
> I can definitely bring my experience in working with OEMs and managing large fleets to ChargePoint. Ultimately, however, my goal is to drive ChargePoint’s success in Europe through all the distribution channels we operate in.
Thank you very much for the conversation!